
For the same 40-year-old couple, same $60K USD-equivalent spending target, same 80/20 portfolio, and the same 55-year classic Monte Carlo model with fitted return shapes, Retirement Lab produced a wide spread: Thailand and Malaysia cleared the 95% success threshold at $650K and $690K, while Switzerland required about $2.73M. That is a $2.08M spread before changing the household, market assumptions, or spending target.
This article compares the 26 tax-residence countries Retirement Lab supported when the ranking was first run in August 2026. Retirement Lab has since added Chile, Czechia, Hungary, South Africa, and Vietnam, bringing the supported set to 31; those five are not in this ranking. It is a complete ranking of that 26-country set, not a worldwide ranking of every possible destination.
| Rank | Country | Portfolio for 95% target | Wealth tax modeled | World Bank price level (US=1.00) |
|---|---|---|---|---|
| 1 | Thailand | $650K | no | 0.31 |
| 2 | Malaysia | $690K | no | 0.32 |
| 3 | Brazil | $1.04M | no | 0.47 |
| 4 | Panama | $1.11M | no | 0.51 |
| 5 | Mexico | $1.27M | no | 0.59 |
| 6 | Cyprus | $1.34M | no | 0.64 |
| 7 | Malta | $1.35M | no | 0.63 |
| 8 | Greece | $1.35M | no | 0.60 |
| 9 | UAE | $1.43M | no | 0.70 |
| 10 | Costa Rica | $1.43M | no | 0.64 |
| 11 | Portugal | $1.48M | no | 0.60 |
| 12 | Spain | $1.49M | yes | 0.64 |
| 13 | Japan | $1.50M | no | 0.66 |
| 14 | Singapore | $1.56M | no | 0.78 |
| 15 | Uruguay | $1.58M | no | 0.73 |
| 16 | Italy | $1.69M | yes | 0.68 |
| 17 | UK | $1.79M | no | 0.87 |
| 18 | Germany | $1.82M | no | 0.76 |
| 19 | Belgium | $1.84M | no | 0.81 |
| 20 | Canada | $1.88M | no | 0.91 |
| 21 | France | $1.89M | no | 0.78 |
| 22 | Australia | $1.90M | no | 0.94 |
| 23 | Austria | $1.95M | no | 0.78 |
| 24 | US | $2.11M | no | 1.00 |
| 25 | Netherlands | $2.47M | yes | 0.80 |
| 26 | Switzerland | $2.73M | yes | 1.26 |
How we ran it
The household was deliberately plain: a couple, both age 40, retiring in 2026 with an 80/20 global equity/bond portfolio, annual rebalancing, and $60,000 of year-0 spending before country cost-of-living adjustment. Retirement Lab then converted the target spending into local-currency spending using the COL and FX tables in the run metadata, applied country tax rules year by year, and ran 10,000 independent-year Monte Carlo paths with Retirement Lab's default return assumptions (computed from 1871–2024 history), fitted per-asset return shapes, and Typical market turbulence (simulation_mode=monte_carlo_iid, assumptions 2026-10-18.v1). Success means the portfolio stayed above zero through age 95, a 55-year retirement.
Why age 95? Average life expectancy is not the same thing as a fixed planning endpoint for a couple. The Society of Actuaries' longevity guidance emphasizes both the chance of living beyond average life expectancy and the last-survivor problem for couples. Age 95 makes the comparison conservative enough that a retirement beginning at 40 does not quietly stop while one spouse may still be alive.
The number in the ranking is the smallest tested USD-equivalent starting portfolio that cleared a 95% simulated success target in its linked 10,000-path production run. In other words, the ranking does not compare countries at different target probabilities: the portfolio is the variable, and 95% is the common target. A local common-path search located each threshold; production cases below 95% were increased and rerun. We did not keep rerunning unchanged inputs to select favorable samples.
These runs were computed in October 2026 under Retirement Lab's 2026-10-18.v1 result semantics. Before publication, four of the linked cases (Thailand, the US, the Netherlands and Switzerland) were re-run on 2026-10-21.v1 with the same inputs; each moved by 0.3 percentage points or less, which is the sampling noise between two independent 10,000-path runs. A later engine change can move a threshold, so a scenario opened after one may not reproduce the exact figure published here. The linked scenarios stay useful as editable starting points; treat the exact figures as a dated snapshot rather than a live readout.
France is the only row without a linked scenario. Its benchmark sets PUMa/CSM health-contribution inputs that the automated interface used for the other production runs does not accept, so the France figures come from the same Retirement Lab engine run directly at the same assumptions version, with the same household and the same 10,000-path count.
Updated October 2026. This ranking was first published in August 2026 under 2026-06-23.v1, on an engine that stretched the left tail of a bell curve by a fixed factor (skewness_factor=2.0). Every row has been rerun on the current engine, whose default return assumptions, inflation default, and per-asset return shapes are computed from 1871–2024 history. In August, Malaysia and Thailand tied at $720K and Switzerland needed $2.89M; on the current engine Thailand needs $650K and Switzerland $2.73M. The France row also changed basis: the table now shows the no-relief case, with the case in which all U.S.-source income qualifies for the French tax credit reported beside it, where the August table showed the qualifying case.
Where the cost-of-living numbers come from
The cost multiplier is the World Bank's 2024 Price level index for households and NPISH final consumption (PA.NUS.PRVT.PLI), downloaded after its 2026-07-13 update and licensed CC BY 4.0. The published US value is 100; we divide every country's index by 100, making the US 1.00. No hand-tuned country overrides remain in this ranking.
This is a broad national household-consumption basket, not a retiree-only basket. The International Comparison Program methodology describes food and beverages, clothing and footwear, utilities, furniture and appliances, pharmaceuticals and private healthcare, vehicles and transportation, communications, restaurants and accommodation, recreation, personal care, private education, and other household goods and services. Housing is included: the housing survey uses rents for comparable dwellings where rental markets are representative, or dwelling-stock quantity and quality data where they are not.
That breadth is useful for a 26-country baseline, but it is still a national average. Also note that the price level is a 2024 observation used to scale a 2026 spending target; it is not adjusted forward for country-specific inflation between those years. It does not represent a particular city, an expat neighborhood, a retiree's healthcare mix, or whether the household rents or owns. Those choices should be modeled by replacing the $60,000 spending input rather than treating this ordering as a universal affordability ranking.
The simulation also does not project future exchange-rate paths or country-specific inflation. It uses one year-0 FX conversion and applies the same 2.0% annual inflation assumption in every country. That keeps the country comparison controlled, but it is not a 55-year forecast of what a USD portfolio will buy in each local currency.
This is a scenario comparison, not an objective country affordability index. The cost-of-living inputs scale the same $60,000 US spending target and therefore drive a substantial part of the result. Different housing, healthcare, exchange-rate, tax-residency, or lifestyle assumptions can change both the required portfolio and the ordering.
The top five
The first break in the ranking is the striking one: Thailand and Malaysia both stay below $1M, at $650K and $690K. Their World Bank price levels are 0.31 and 0.32. The $40K gap between them is small next to everything that follows; both sit in a category of their own.
Brazil and Panama form the next tier, at $1.04M and $1.11M. The $70K gap between them is small next to the $350K step up from Malaysia, so the useful signal is the cluster rather than the exact order.
Mexico closes the group at $1.27M. Its 0.59 price level remains well below the US baseline, but the top five still span $620K. “Lower-cost country” is not one financial category once taxes and a 55-year horizon enter the simulation.
The bottom five
Australia and Austria open the bottom five, at $1.90M and $1.95M, with World Bank price levels of 0.94 and 0.78. Their modeled mechanics differ, but neither receives the large spending discount seen in the leading country cases.
The US case, at $2.11M, is the useful baseline. It receives no cost-of-living discount in this comparison. Moving above or below it reflects the combined effect of the country price level and modeled tax treatment, not either input in isolation.
The Netherlands and Switzerland create a bottom-end cliff. The broad middle from Cyprus at $1.34M through the US at $2.11M fits inside a $770K band. The next step jumps $360K to the Netherlands, then another $260K to Switzerland. That discontinuity is the story; the tax mechanics behind it come next.
Tax surprises
The Netherlands is the clearest tax surprise. Its World Bank price level was 0.80—below the UK, Canada, Australia and the US—yet its required portfolio was second-highest at $2.47M. In this modeled case, Box 3-style deemed-return taxation substantially changed the result relative to what a cost-of-living screen alone would imply.
Spain is another useful warning against reading the table as a pure affordability ranking. Its price-level input was 0.64, close to Cyprus and Malta, but the modeled wealth tax begins to matter as the portfolio grows. Spain landed at $1.49M, compared with $1.34M for Cyprus and $1.35M for Malta.
France needs a more explicit qualification than the other rows, because the France-US treaty result depends on the source and type of a household's actual holdings. Every row in this ranking, France included, models the same married couple who are both U.S. citizens, file the modeled U.S. return jointly, share one French tax household (foyer fiscal), and are French tax residents for the full calendar year. Those facts are pinned by the versioned assumption pack france-us-retiree-couple-2026-v1 (v1), disclosed in full in the methodology.
The sortable France entry (row 21) is the no-relief case. It applies no French tax credit for qualifying U.S.-source income, because a generic 80/20 global portfolio does not establish the source/payor, beneficial-ownership, and U.S.-reporting conditions that credit requires. The simulation shows a $1.89M threshold and 87.2% success at $1.50M.
Alongside it, the same paths were rerun as a hypothetical case in which 100% of the modeled investment income and realized gains qualifies for that credit (French Article 24(1)(b) / English Article 24(2)(b) of the France-US treaty): $1.65M and 93.4%. That is a disclosed sensitivity, not a finding about this portfolio or any reader's holdings; a household whose investments are a mixture of qualifying and non-qualifying assets would fall between the two modeled endpoints. The PUMa supplementary health contribution (CSM / cotisation subsidiaire maladie) is modeled separately from the French PFU in both cases, and mutuelle costs stay separate from both.
Switzerland combined the highest price level in the set—1.26 of the US baseline—with cantonal wealth taxation, producing the highest required portfolio at $2.73M. The UAE and Panama show the opposite pattern: their modeled personal-tax treatment is light, but their positions still reflect the spending adjustment as well as tax.
These are outputs of the calculator's default country cases, not claims about every household's tax liability. Tax residence, citizenship, account wrappers, source of income, region, and special regimes can change the result.
A dual view: target portfolio versus a fixed $1.5M
The first view asks, “How much portfolio did this country case need to reach the common 95% target?” The second holds the portfolio constant at $1.5M and asks what success probability the same model produced.
$1.5M is a useful fixed reference because $60,000 is exactly 4% of $1.5M. That makes the second view a recognizable 4% starting-withdrawal case while preserving the same couple, age-95 endpoint, 80/20 portfolio, cost-of-living adjustment, and country tax model. These are separate 10,000-path runs, not probabilities borrowed from the threshold search.
| Threshold rank | Country | Success with $1.5M |
|---|---|---|
| 1 | Thailand | 99.9% |
| 2 | Malaysia | 99.9% |
| 3 | Brazil | 99.0% |
| 4 | Panama | 98.6% |
| 5 | Mexico | 97.8% |
| 6 | Cyprus | 96.8% |
| 7 | Malta | 96.8% |
| 8 | Greece | 97.0% |
| 9 | UAE | 96.6% |
| 10 | Costa Rica | 96.1% |
| 11 | Portugal | 95.8% |
| 12 | Spain | 95.3% |
| 13 | Japan | 95.6% |
| 14 | Singapore | 94.2% |
| 15 | Uruguay | 95.2% |
| 16 | Italy | 92.5% |
| 17 | UK | 91.0% |
| 18 | Germany | 90.1% |
| 19 | Belgium | 89.4% |
| 20 | Canada | 89.7% |
| 21 | France | 87.2% |
| 22 | Australia | 88.8% |
| 23 | Austria | 88.9% |
| 24 | US | 86.8% |
| 25 | Netherlands | 80.7% |
| 26 | Switzerland | 69.2% |
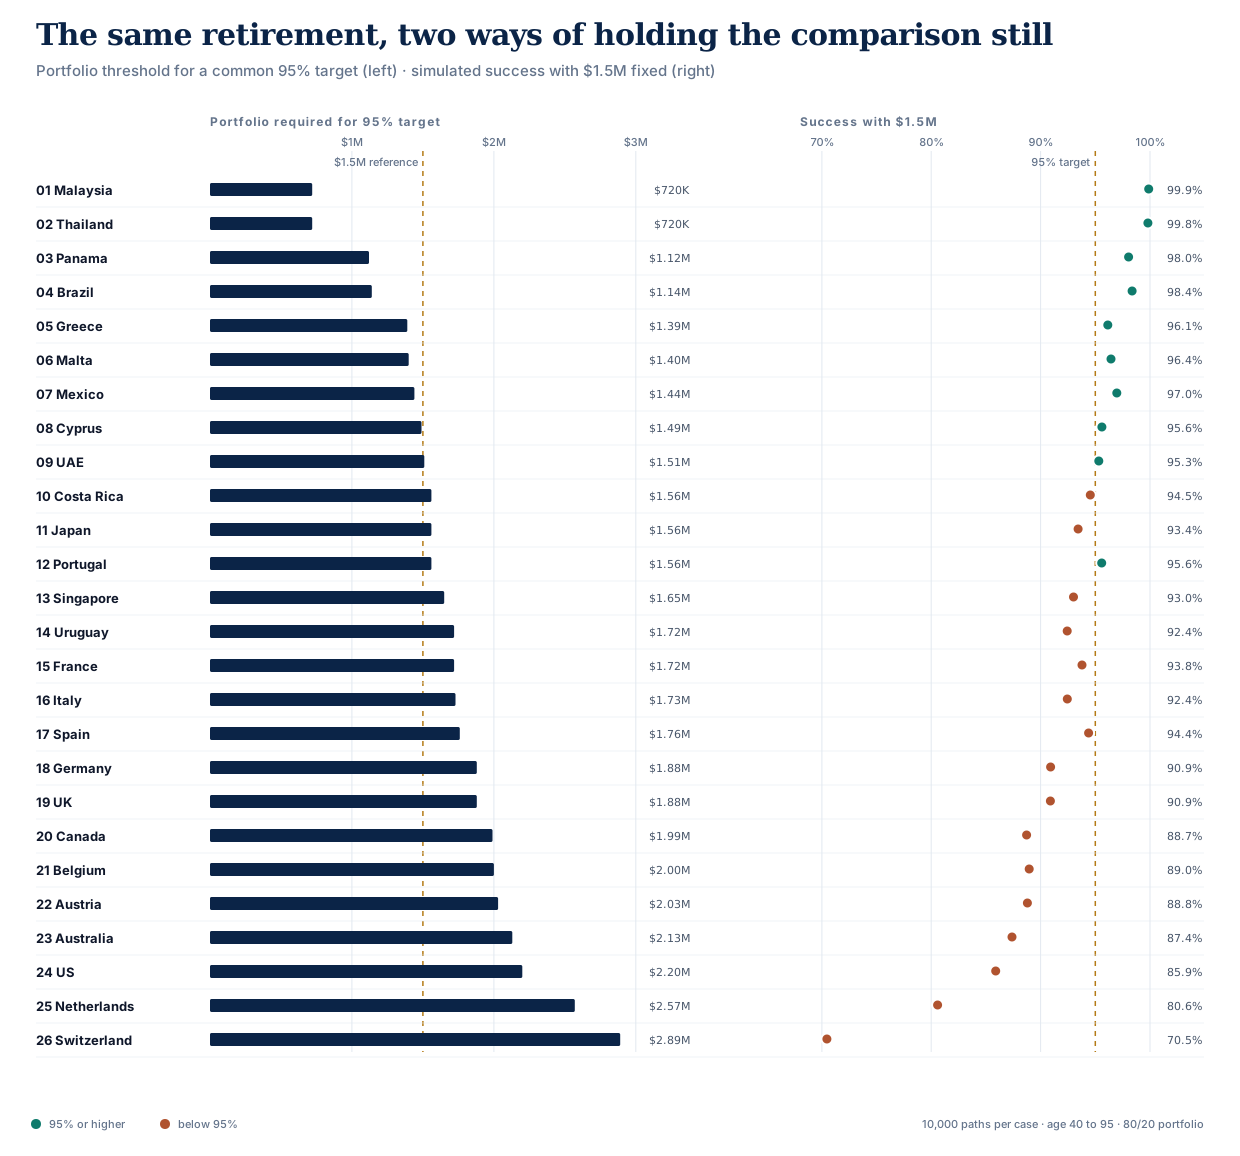
Countries stay in threshold rank order in both panels. The second panel holds the portfolio at $1.5M; it does not reuse the probability from the threshold search.
Re-run this with your own numbers
The country links in the ranking open the exact published cases (every row except France, whose benchmark runs outside the shareable production path). To replace the age, spending, portfolio, and country instead of inheriting one country's assumptions, start a new Retirement Lab scenario.
Each linked scenario includes the country-specific assumptions and known simplifications used in that run. Expand its country tax-policy pill to see them. The broader engine is described on the methodology page.